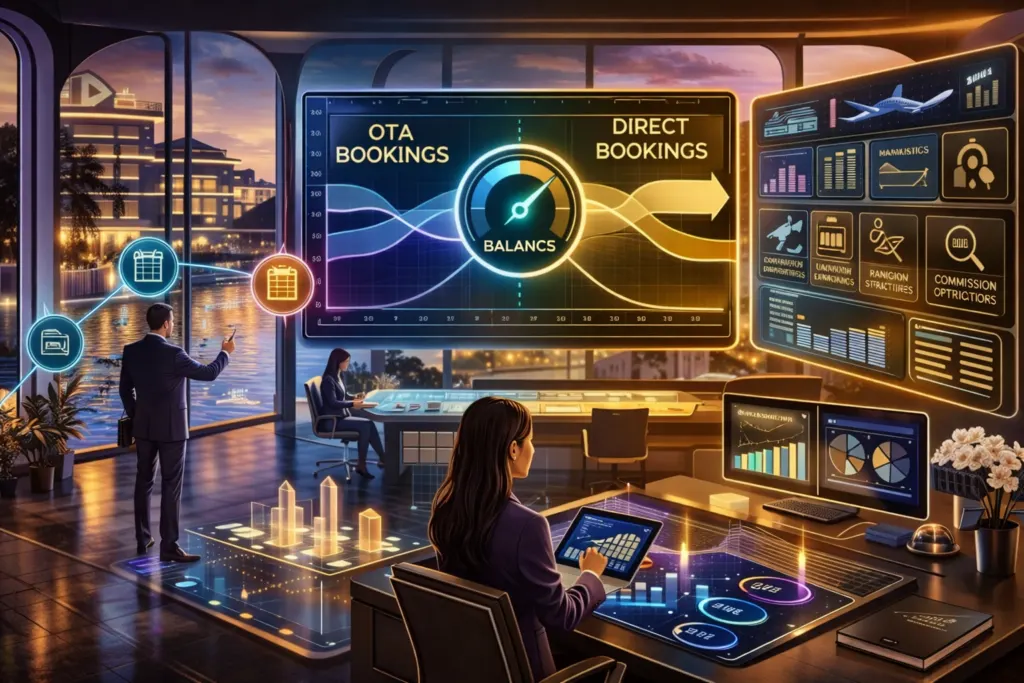
Hotels optimize their channel mix by prioritizing net revenue yield over gross booking volume using Net RevPAR tracking. While Online Travel Agencies (OTAs) act as critical top-of-funnel demand generators, hoteliers balance this dependency by employing automated rate parity fences, offering value-add direct incentives (such as complimentary upgrades or flexible cancellation paths), and utilizing metasearch bidding strategies. Shifting volume to direct channels allows hotels to reclaim 15% to 25% in commission leakages while capturing first-party guest data, essential for lowering lifetime guest acquisition costs (CPA).
Table of Contents
- Understanding Channel Economics
- The Real Role of OTAs in Your Distribution Strategy
- Why Direct Bookings Generate More Net Revenue
- Building a Channel Mix Strategy
- Rate Parity and Channel Differentiation
- The Direct Booking Engine: Converting OTA Lookers
- How Propeter Supports Channel Mix Decisions
- Frequently Asked Questions
Ask most hoteliers what percentage of their bookings come through OTAs and they’ll know the number. Ask what percentage of their net revenue comes through OTAs and the answer is very different — because OTA bookings, after 15–25% commission, deliver substantially less actual revenue per pound of gross booking value than a direct reservation at the same rate.
Channel mix optimisation is the discipline of managing this distribution equation strategically — understanding the true cost of each channel, the value of the guests it delivers, and the levers available to shift mix towards higher net-revenue channels without sacrificing the demand generation that OTAs provide.
Understanding Channel Economics
The economics of hotel distribution vary dramatically by channel. Understanding the true cost-per-booking for each channel — including not just the direct commission but the cost of the technology, the incremental marketing required to maintain presence, and the value of the guest data — is the foundation of intelligent channel management.
OTA Economics
The major OTAs — Booking.com, Expedia, Agoda, Hotels.com — charge commissions ranging from 15% to 25% of the booking value, with averages typically around 17–18% for independent hotels. For a hotel with an average daily rate of £150 and 10,000 annual room nights through OTAs, a 17% commission represents £255,000 in annual costs. This makes OTA distribution the single largest controllable cost line in most independent hotel P&Ls.
Beyond the headline commission, OTA economics include the cost of rate parity obligations (which limit the hotel’s ability to offer lower rates on other channels), the limited access to guest data (OTAs own the guest relationship in the first booking), and the algorithmic ranking dynamics that often require participation in OTA visibility programmes (such as Booking.com’s Genius discounts) to maintain ranking.
Direct Channel Economics
Direct bookings — through the hotel’s own website, phone, email, or walk-in — carry no commission but are not free. The cost of a direct booking includes website hosting and booking engine fees (typically 1–3% of booking value for SaaS platforms), digital marketing to drive traffic (SEO, paid search, metasearch), and the staff cost of handling enquiries. Total direct booking cost typically ranges from 5–8% of booking value — meaningfully lower than OTA commissions but requiring active investment to maintain.
15–25%Typical OTA commission range
5–8%Typical direct booking cost
The Real Role of OTAs in Your Distribution Strategy
OTAs are often discussed in adversarial terms by hoteliers — the commissions are high, the terms are demanding, the guest data is withheld. But this framing misses a crucial reality: OTAs are extraordinarily effective demand generation engines for hotels that couldn’t otherwise reach global audiences.
A boutique hotel in Edinburgh has access to a guest searching from Singapore, Tokyo, or Buenos Aires through Booking.com’s global platform. Without that OTA listing, that guest discovers a competitor instead. For many independent hotels, OTAs are not a costly alternative to direct bookings — they’re the primary source of international leisure demand that the hotel couldn’t capture directly.
The strategic framing that changes outcomes is this: OTAs are acquisition channels, not retention channels. Their highest value is introducing new guests to your property. Once a guest has stayed, the relationship shifts — they know who you are, and you have the opportunity to convert their next visit to a direct booking through loyalty programmes, email marketing, and direct incentives.
The Billboard Effect
Research consistently demonstrates the “billboard effect” — the phenomenon where OTA listings generate direct bookings on the hotel’s own website from guests who discover the property on Booking.com or Expedia but then book directly after researching further. OTA presence thus contributes to direct booking volume as well as OTA booking volume. This is why simply removing OTA listings rarely improves net revenue.
Why Direct Bookings Generate More Net Revenue
The financial case for direct bookings is clear at the transaction level: every percentage point shift from OTA to direct, at constant rates, increases net revenue by approximately 10–15 basis points of total revenue (depending on commission rates). For a £5 million annual revenue hotel, shifting 10% of bookings from OTA to direct could yield £75,000–£125,000 in additional net revenue annually.
But the financial advantage extends beyond the commission saving. Direct guests tend to exhibit higher-value booking behaviour across multiple dimensions:
- Higher ancillary spend: Guests who book directly often purchase F&B, spa, parking, and activities at higher rates than OTA guests, partly because the direct booking experience allows better upsell presentation
- Better cancellation behaviour: Direct bookings on non-refundable rates have lower cancellation rates than equivalent OTA bookings, as direct guests are typically more committed and less likely to book simultaneously across multiple platforms
- Guest data ownership: Direct bookings give the hotel full access to guest contact details, enabling pre-arrival communication, post-stay follow-up, and email marketing for repeat bookings
- Loyalty potential: Direct bookers who enrol in loyalty programmes have demonstrably higher lifetime value and return booking rates
Building a Channel Mix Strategy
An effective channel mix strategy starts with measurement. Hotels need channel-level reporting that captures not just gross booking volume but net revenue after costs, plus ancillary spend, cancellation rates, and repeat booking rates by channel. Most PMS systems under-report channel performance; sophisticated revenue platforms provide the complete picture.
Segmenting by Demand Type
Optimal channel mix varies by demand type. For transient leisure guests, OTAs dominate discovery but direct channels can capture a significant share with the right incentive structure. For corporate travellers, GDS and direct corporate rate agreements typically generate higher-quality demand than OTAs. For groups, direct sales are almost always the appropriate channel. Managing channel strategy by segment rather than in aggregate produces better outcomes.
Dynamic Channel Management
Channel allocation should respond to demand conditions. During high-demand periods when rooms will fill at high rates regardless of channel, reducing OTA availability and pushing inventory towards direct and higher-margin channels makes sense — there’s no demand generation value from OTA presence when demand already exceeds supply. During low-demand periods, OTA availability and visibility investment may be worth the commission cost to fill rooms that would otherwise go empty.
Rate Parity and Channel Differentiation
Rate parity clauses in OTA contracts historically required hotels to offer the same public rate on every channel, preventing hotels from undercutting OTAs on their own website. What is permitted today varies by OTA contract and by jurisdiction, and regulators in several markets have restricted parity clauses in recent years. Most hotels can still differentiate through non-public rates (member-only or signed-in rates), packaged value and loyalty benefits. Check your own OTA agreements before pricing below OTA rates on any channel, and take legal advice where the position in your market is unclear.
Within the constraints of any remaining parity obligations, hotels can differentiate the direct booking proposition through non-rate value-adds: complimentary breakfast, early check-in or late check-out, room upgrade priority, or flexible cancellation terms not available through OTA channels. These additions make the direct channel more attractive than the OTA at the same headline rate — a legitimate and effective tool for driving channel shift.
The Direct Booking Engine: Converting OTA Lookers
The hotel’s own website is the primary arena for capturing direct bookings from guests who discover the property on OTAs. The quality of the booking engine — its design, speed, mobile optimisation, and upsell capability — directly determines what percentage of those visitors convert to reservations versus abandoning back to Booking.com.
Key elements of a high-converting direct booking engine include clear best-rate messaging, compelling room type differentiation with quality photography, transparent pricing without surprise fees, one-click-to-book flows that minimise abandonment, and integrated upsell of packages, breakfast, and add-ons at the point of booking rather than at check-in.
How Propeter Supports Channel Mix Decisions
Propeter is built on the principle that channel economics and pricing belong in the same view. Propeter brings competitor rates into its pricing recommendations — from your Lighthouse subscription, if you have one, and from public listings collected through a third-party data provider. Competitor rates refresh hourly for the next 14 nights and progressively less often for dates further out. Propeter is not a channel manager: approved rates are distributed through your connected PMS and channel manager, and Propeter reports pace, pickup and channel mix so you can see what each channel is really contributing.
Where your hotel subscribes to Lighthouse, that compset data can be used directly; otherwise public listings collected through a third-party provider give revenue managers market visibility without manual rate checking.
On the direct channel side, Propeter’s commission-free booking engine prices from the same rate engine as the rest of your distribution — the same base rate, inventory position, promotions, loyalty discounts and guardrails — so the direct channel always presents a rate consistent with current demand, and upsell offers are priced to maximise total booking value rather than room revenue alone.
The result is a channel mix strategy that uses OTAs for their genuine demand-generation strengths while systematically building the direct booking share that maximises net revenue.
Frequently asked questions
What is the exact mathematical formula to calculate Net RevPAR across different channels?
Net RevPAR evaluates the true cash efficiency of your distribution channels by subtracting customer acquisition expenses. The calculation is: Net RevPAR = (Total Room Revenue – Distribution Commissions – Transaction Fees – Channel Marketing Costs) / Total Available Rooms. Tracking this figure instead of standard gross RevPAR prevents revenue managers from mistaking high-volume, high-commission OTA spikes for healthy profitability.
How does wholesale rate leakage disrupt a hotel’s channel mix optimization?
Wholesale rate leakage occurs when bedbanks or static wholesale contracts unbundle B2B room blocks and resell them to un-fenced, discount consumer OTAs. This breaks public rate consistency, undercuts your highly profitable direct channel, and forces you into lower net-margin occupancy. Resolving this requires implementing automated rate shoppers that instantly flag un-parity and utilizing dynamic, real-time API wholesale agreements that cut off violators.
How can a hotel accurately measure its Direct Booking CPA against OTA commissions?
To verify if direct bookings are truly cheaper than OTAs, you must calculate the Direct Cost Per Acquisition (CPA). This formula aggregates your total web development amortizations, booking engine SaaS fees, payment processor rates, and metasearch ad spending (Google/TripAdvisor) divided by total direct booking revenue. If your Direct CPA tracks under 8–10%, investing marketing capital into direct channels yields higher margin returns than a baseline 15–20% OTA commission.
What is an inventory fencing strategy for channel mix optimization?
Inventory fencing involves intentionally limiting the types of rooms or lengths of stay accessible on third-party channels during high-demand or compressed dates. Rather than pulling your property off OTAs entirely, a revenue system applies a fence—such as restricting base-tier room availability to OTAs while keeping premium suites exclusive to your direct booking engine. This captures broad top-of-funnel OTA visibility while protecting peak-margin inventory for direct shoppers.
Optimise Your Channel Mix with Propeter
See how Propeter’s pricing, channel reporting and commission-free booking engine work with your channel manager to grow net revenue across your distribution mix.
Related Articles
How to choose hotel revenue management software for independent properties in Australia
The best hotel revenue management software for independent Australian properties is not determined…
Propeter vs Competitors: Which Hotel Revenue Management Solution Wins?
Propeter is a revenue management and pricing system for hospitality that works with your PMS, with a direct booking engine, guest CRM, loyalty…
Low Season Hotel Strategy: Maximize Occupancy & Revenue (2026)
Maximising hotel occupancy and revenue in low season is not about discounting your…
Model the opportunity
Estimate what better pricing could be worth using your own assumptions.